IREN Triples AI Cloud Revenue—and Slips the $4B ARR Target Into January
IREN's AI Cloud nearly tripled to $200M and operating ARR hit $1B, but the >$4B ARR milestone moved from year-end into January (maybe February) after Microsoft asked for a network redo on ~200 MW in Texas. Here's the scorecard, the delay, and what the funding plan actually says.
Tom Pechulis, , 7 min read
Yesterday I said I'd watch IREN after the close. They reported. The print is the story investors wanted on the demand side—and the slip they feared on the delivery side.
AI Cloud revenue nearly tripled to $200 million. Operating ARR doubled to $1 billion. The >$4 billion ARR target that was supposed to be live by year-end is now January 2027, and management says it may run to the end of February. The customer behind the design change is Microsoft. No penalties, per Reuters. The capacity is still contracted and, per IREN, still funded.
Everything below comes from IREN's Nov 5 Q1 FY27 press release, its Form 10-Q for the quarter ended Sep 30, 2026, the earnings call transcript, and coverage from Reuters/CNA and CNBC.
TL;DR
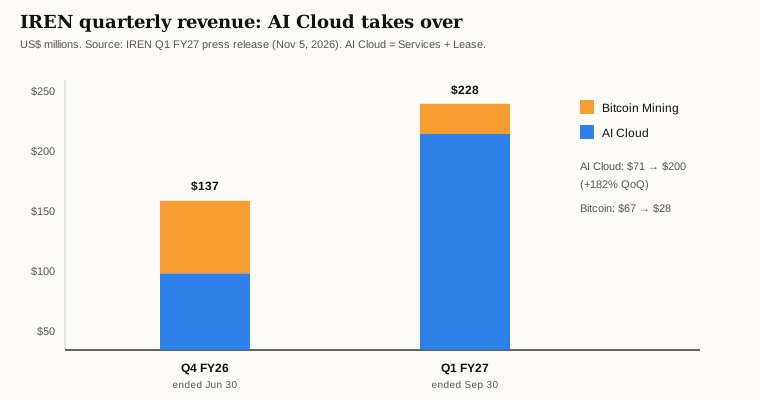
- The print: total revenue $228M (+66% QoQ); AI Cloud $200M (+182% QoQ from $71M); Bitcoin mining $28M (down from $67M); adjusted EBITDA $66M (29% margin); net loss $(263)M (PR).
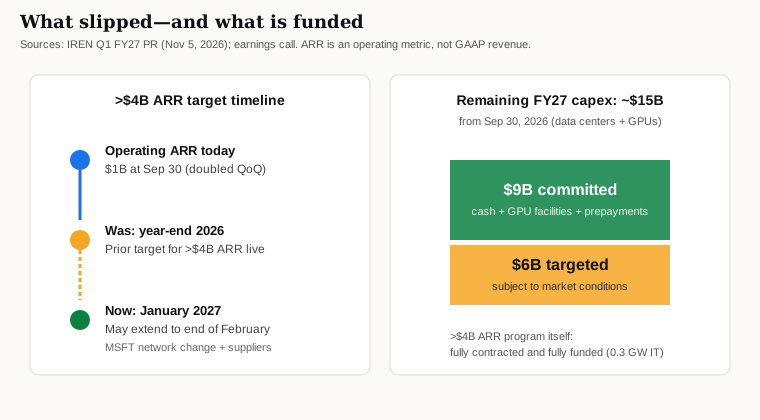
- The slip: >$4B ARR, previously year-end 2026, now targeted for January 2027, may extend to end of February. Reasons: a customer-requested network redesign plus supplier timing. Customer = Microsoft; ~200 MW in Texas (PR; CNBC; Reuters).
- Why the change: Microsoft asked to reconfigure/upgrade network gear so the full 200 MW can serve latest-generation frontier models. Horizon 1 already handed over with NVIDIA Exemplar status; Horizons 2–4 are late-stage (call; PR).
- Demand color after quarter-end: ~$22M per IT-MW on a five-year deal with the customer prepaying ~90% of GPU capex; short-term deal at $40M per IT-MW; H100s recontracted at double prior pricing (PR).
- Funding: remaining FY27 capex ~$15B from Sep 30—$9B cash/committed GPU financing/prepayments, $6B still "target… subject to market conditions." Capital commitments $18.95B (up from $13.81B). GPU hardware on the books $5.82B (from $2.04B) (PR; 10-Q).
- Stock tape: closed ~−17% into the broader AI selloff; ~+4% after hours on the print (Reuters). CNBC notes a ~26% post-election drop and ~55% over the past month (CNBC).
Quick jargon decoder
| Term | Plain English |
|---|---|
| ARR (annualized run-rate) | Take today's contracted GPU/hour price × 8,760 hours, plus storage/ancillaries. It is an operating metric, not GAAP revenue. Recognized revenue can be much lower (PR note 4). |
| IT-MW / revenue per megawatt | Rough annual revenue for one megawatt of IT load (the power that feeds the computers). IREN quotes contract economics this way. |
| Neocloud | GPU cloud / AI infra providers that aren't the big three hyperscalers—CoreWeave, IREN, Nebius, Nscale, and peers. |
| NVIDIA Exemplar Cloud | Nvidia's validation badge that a cluster (here GB300 NVL72 at Horizon 1) meets their reference design/performance bar (PR). |
| Investment-grade counterparty | A customer (or guarantor) with a BBB-/Baa3-or-better credit rating. IREN says ~two-thirds of backlog sits there (PR). |
| Prepayment | Customer pays a big chunk of GPU cost up front. On the new five-year deal, ~90% of associated GPU capex (PR). |
Think of ARR as the speedometer and GAAP revenue as the odometer. The speedometer jumped. The date when it hits the next milestone moved right by a month or two.
The scorecard
Three months ended Sep 30, 2026 vs Jun 30, 2026 (PR):
| Sep 30, 2026 | Jun 30, 2026 | |
|---|---|---|
| AI Cloud revenue | $200M | $71M |
| — Services | $135M | $71M |
| — Lease | $65M | — |
| Bitcoin mining | $28M | $67M |
| Total revenue | $228M | $137M |
| Net income (loss) | $(263)M | $(684)M |
| Adjusted EBITDA | $66M | $19M |
AI Cloud segment gross margin stayed at 86% before depreciation. Bitcoin is being actively decommissioned so GPUs can take the halls; management wants that transition substantially done this quarter (call).
Backlog rose 22% sequentially to $20.3 billion, with roughly two-thirds tied to investment-grade counterparties. Named credit anchors: Microsoft, Nvidia, and 13 other customers (PR).
On the call, CFO Anthony Lewis said they exit September with $1B of operating ARR and expect roughly one-quarter of that amount as revenue in the December quarter—and not material revenue yet from the incremental Horizon/Mackenzie capacity that lands late Dec / early calendar 2027 (call; CNBC).
What Microsoft actually asked for
Co-CEO Daniel Roberts put the delay first on the call, which is the right move when the tape is already pricing delivery risk.
- Customer-requested design change outside the original scope.
- Supplier timing on remaining equipment to finish commissioning.
On the Q&A, Roberts named Microsoft and the purpose: reconfigure and upgrade network infrastructure so the 200 MW can serve latest-generation frontier models. Horizon 1 was already handed over (announced back in August); the ask came after. Incremental capex for the network change is "entirely immaterial" versus the cluster—new cables, labor, a different install method—not a rack redesign (call).
Construction color from the call: Horizon 2 built with power on at the rack across halls and Dell commissioning; Horizon 3 GPUs on site and halls energized; Horizon 4 GPUs arriving in coming weeks. Roberts: if suppliers deliver, January; if late, end of February—and he noted suppliers have been late across the industry this year (call).
Reuters/CNA: the Microsoft delay does not trigger financial penalties because it was customer-requested. Same pieces also relay a Bloomberg report that Microsoft is tightening oversight of some neocloud projects (IREN, Nebius, Nscale) and weighing how much more business to send that way versus building its own. That is Bloomberg's reporting, not something IREN confirmed on the call—treat it as reported, not proven (Reuters/CNA).
One structural point Roberts leaned on: owning the stack made the yes possible. An asset-light neocloud renting colo would have had to go back to the landlord. Vertical integration is the bull case IREN keeps selling, and this change order is the live demo (call).
Funding: $15B left, $9B committed, $6B "market"
This is the part that matters if you're underwriting neocloud credit after a midterm scare.
From the PR:
- Remaining planned FY27 capex ≈ $15B from Sep 30 (data centers + GPUs).
- Of that: $9B cash and committed GPU financing and prepayments.
- $6B "target" GPU financing, prepayments, data-center financing, and other corporate sources—subject to market conditions.
Balance-sheet snapshots (PR; 10-Q):
- Total assets $20.6B, including $6B of data-center assets with 20-year useful lives (unencumbered, per management).
- Cash and equivalents $3.5B; restricted cash ~$2.3B (mostly locked for GPU financing).
- Total debt ~$10.2B (call; carrying value of debt + finance leases in the PR's net-debt recon).
- Capital commitments $18.95B at Sep 30, up from $13.81B three months earlier (10-Q Note 24).
- GPU hardware $5.82B (from $2.04B); construction in progress $4.61B (10-Q Note 11).
Call color on cost of capital: $6.5B of GPU financing since May at 6% to 9.5%. Capex plan for the rest of FY27 was flexed down from prior guidance—not for lack of demand, management says, but because "capital markets have become more selective" and they will not "grow at all costs" (call).
The >$4B ARR program (the 0.3 GW IT slice) is what they call fully contracted and fully funded. The $6B gap sits against further capacity targets, including the 0.8 GW data-center capacity by end of calendar 2027 (PR notes 5 and 12).
Pricing is still going the wrong way for buyers
If the stock is pricing a funding crunch, the contract book is pricing a capacity crunch.
- Five-year contract ≈ $22M per IT-MW, with customer prepaying ~90% of associated GPU capex.
- Short-term contract at $40M per IT-MW.
- Expanded an existing deal with a "Leading Frontier AI Lab."
- Older H100s recontracted at double the prior price, on a multiyear term—not a spot spike.
During Q1, contracted pricing was up +11% on 3-year deals and +12% on 5-year deals versus the prior period's book (PR). Illustrative paybacks on the call: around 18 months on GPUs at ~$20M/MW with 50% GPU prepay, or faster with higher prepay (call).
That is the disconnect Roberts keeps naming: public markets asking "can you finance it?" while customers keep writing bigger checks and prepaying the silicon.
My take
- Bull case: this is a change-order slip, not a demand hole. Microsoft asked for more network so 200 MW can run the newest frontier workloads; IREN said yes; Exemplar is already on Horizon 1; the >$4B ARR block is funded; post-quarter pricing and 90% GPU prepays are as strong as anything in the neocloud tape. Owning land, power, and shells is doing real work when a hyperscaler wants a mid-build redesign.
- Bear case: a month or two is fine once. Markets that just punished the complex after midterms will treat every further slip as proof the schedule was soft. $6B of the remaining $15B FY27 capex is still "subject to market conditions." Capital commitments already sit near $19B. Customer concentration is real—three AI Cloud customers were 28%, 24%, and 18% of revenue this quarter (10-Q). Bloomberg's reported Microsoft oversight tightening, if it sticks, is a demand-mix risk even if this specific change order is friendly.
- Where I land: believe the print and the change-order story; underwrite the $6B funding gap and the January/February delivery window as the actual risks. ARR is a speedometer—useful, not GAAP. I'd rather see Horizon 2–4 accepted on the new January target than another guidance shuffle. For the broader neocloud complex, the message rhymes with yesterday's cosigner piece: delivery and who stands behind the cash flows matter more than headline TCV right now.
What I'm watching
- January (or February) acceptance of the Microsoft/Horizon capacity—the next hard date.
- CoreWeave on Nov 10 and Nebius on Nov 12—same watchlist as the last two posts. Credit-support language, delivery slips, funding gaps.
- Whether IREN closes data-center financing against Horizons 1–4 (AAA-ish Microsoft cash flows on owned shells) and the next GPU package for Childress.
- How much of the $6B "market" bucket gets locked before Vera Rubin supply gets scarce later in 2027—management flagged VR as "exceptionally scarce" next year (call).