Nvidia Reports Tuesday, Anthropic Prices Wednesday: The AI Trade's Split-Screen Week
The two biggest events in AI infrastructure land 24 hours apart. Nvidia's interim CEO reports against a $108B guide, and Anthropic prices an IPO where Nvidia, AMD, Broadcom, Micron, TSMC, Google and Microsoft are buying $26B of stock. Here's the setup, the numbers that matter, and what I'm watching.
Tom Pechulis, , 10 min read
Sunday is usually a slow news day. Not this week. The two events that matter most for AI infrastructure this year land about 24 hours apart: Nvidia reports its quarter on Tuesday, Nov 17, and Anthropic plans to price its IPO on Wednesday, Nov 18, with trading Thursday. CNBC this morning called it a "split-screen moment" for tech. I think that undersells it. These aren't two separate stories. The chip suppliers are literally buying into the IPO of their biggest customer.
This is a setup post. Nothing has happened yet, so nothing here is a result. Everything is a filing, a guide, a consensus estimate, or reporting from people familiar, and I'll label which is which.
TL;DR
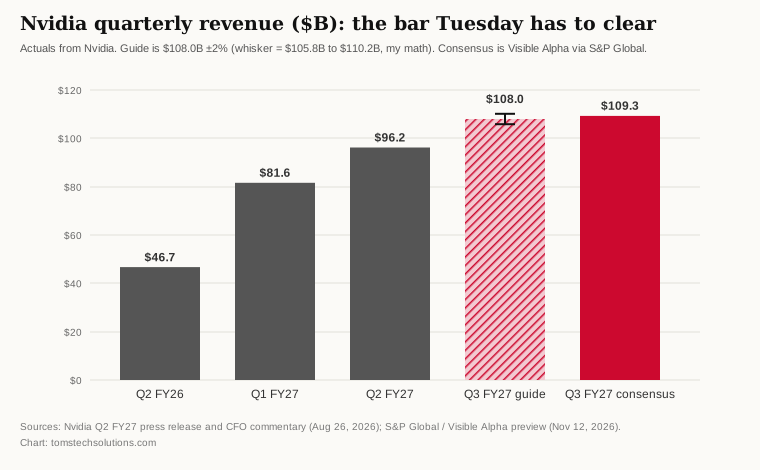
- Tuesday, Nvidia: Q3 FY27 results at about 1:20 p.m. PT, call at 2 p.m. PT. Nvidia guided to $108.0B ±2% with no China data center compute assumed. Visible Alpha consensus is $109.3B. It's the first print with Colette Kress as interim CEO.
- Wednesday, Anthropic: 825M shares at $70 to $78, up to $64.35B raised and up to $1.405T fully diluted value (CNBC). Reuters' sources say the book was six times oversubscribed by Thursday.
- The circle: Nvidia, AMD, Broadcom, Micron, TSMC, Google and Microsoft are buying $26.0B of Anthropic stock at the IPO price. Nvidia's piece is about $10B (Anthropic prospectus). Anthropic, in turn, has about $900.9B of compute and infrastructure commitments.
- My take: Tuesday tells you whether the GPU money is still coming in. Wednesday tells you whether public investors will fund the customer that pays for it. If both go well, the AI trade gets a floor. If either stumbles, the other gets harder.
Quick jargon decoder
| Term | Plain English |
|---|---|
| Guide / guidance | The forecast a company gives for next quarter. Nvidia's $108B is its own estimate. |
| Consensus | The average of Wall Street analysts' estimates. Beating the guide but missing consensus can still disappoint. |
| Pricing | The night before trading, the company and its banks set the final IPO price, inside or outside the range. |
| Oversubscribed | Investors asked for more shares than are for sale. "6x" means orders for six times the shares on offer. |
| Private placement | Shares sold directly to chosen investors, not through the public offering. |
| Fully diluted | Company value counting every share that could exist, including options and convertible notes. |
| Run-rate revenue | Recent revenue annualized. A month's pace times 12. Not the same as a year of actual sales. |
Tuesday: what Nvidia has to show
Here's the bar. Nvidia's Q2 release from Aug 26 reported $96.2B of revenue, up 106% from a year earlier, with data center at $89.0B. For Q3 it guided $108.0B ±2% and gross margin of 74.0% ±50 basis points. That's about 12% sequential growth at the midpoint (my math: 108.0 ÷ 96.2).
What the Street is looking for, per S&P Global's preview using Visible Alpha numbers:
- Total revenue: $109.3B consensus. Other trackers are close: TipRanks cites $108.84B.
- Data center: $101.8B consensus, with estimates from $99.7B to $110.8B.
- Blackwell vs. Rubin: the big debate. In its Blackwell-and-Rubin section, S&P cites Q3 estimates ranging from $37.6B to $65.5B (consensus $48.5B), and about $64.2B of Rubin revenue for the full fiscal year. That's a huge spread, and my guess is it's where the surprise (either way) comes from.
- Valuation: S&P says the fiscal 2027 consensus P/E is about 11x, down from 17x last quarter and 30x historically. My read, in plain English: at that multiple, the market is pricing Nvidia like a company whose best growth might be behind it.
Three things in last quarter's CFO commentary I'll check against the new numbers. These are the SemiAnalysis-brained details, the ones that don't make headlines:
- Supply commitments. They jumped from $119B to $279B in one quarter, "primarily related to the procurement of memory." My read: that's Nvidia locking up memory supply (the filing doesn't say which kind, but HBM, the stacked memory next to each GPU, is the obvious candidate) years ahead. Most of the $279B falls in fiscal 2027 through 2029, so Nvidia is betting on demand at least that far out.
- Who pays, and when. Receivables were $63.1B, and days sales outstanding (how long customers take to pay) rose to 60 days from 45. Nvidia blamed "extended payment terms on large, multi-quarter agreements with certain investment-grade customers." Longer payment terms aren't bad on their own. But it's the kind of thing to watch when the customers are spending ahead of their revenue.
- Guarantees. Nvidia had $108.5B of maximum guarantee exposure, almost all of it the $105B cap backing OpenAI's leases at the SB Energy PORTS-Pike campus in Ohio. I covered why chip vendors co-sign customer debt in Nvidia the cosigner.
And then there's the person on stage. This is Kress's first call as interim CEO after Jensen Huang's resignation on Nov 12 (my explainer is here). Six analysts downgraded the stock on Thursday as reports of his possible exit broke, per TipRanks. Even so, Bernstein's Stacy Rasgon said the fundamentals remain "clearly still intact." That's the tension: the business may print fine and the stock may still not care.
Wednesday: what Anthropic is selling
The deal terms, from the Nov 10 prospectus and CNBC:
- 825M shares at $70 to $78. Anthropic sells about 801.4M; existing holders sell the other ~23.6M. Banks have an option for 123.75M more.
- Up to $64.35B at the top of the range, and up to $1.405T fully diluted value. That's up from the $965B valuation of Anthropic's May funding round.
- Ticker "ANT" on Nasdaq. Pricing Nov 18, trading Nov 19, per people familiar who spoke to CNBC. Those sources also say Anthropic is targeting about 20% retail allocation, versus 5% to 10% for a typical IPO.
- Net proceeds: Anthropic estimates about $84.6B from the IPO plus the private placement at the $74 midpoint, or about $93.7B if the banks' extra-share option is fully used.
Demand, as reported (not confirmed by Anthropic): Reuters says orders hit about 2x on day one and 6x by the end of Thursday, ahead of SpaceX's pace. Bloomberg, via Reuters, reports existing backers will get priority, so some new buyers will get less than they asked for. Anthropic declined to comment to Reuters.
The pushback, also reported: Reuters' sources say investors are asking two questions: can Anthropic hold its lead as Google catches up, and can Claude win beyond coding with knowledge workers? One investor told Reuters Anthropic "had not provided detailed answers to some of the questions raised." That's one person's account, but it's worth knowing.
The circle: suppliers buying their customer
Here's the part I can't stop looking at. Right after the IPO closes, seven companies will buy $26.0B of Anthropic's non-voting Class N stock at the IPO price. The prospectus breaks it out at the $74 midpoint:
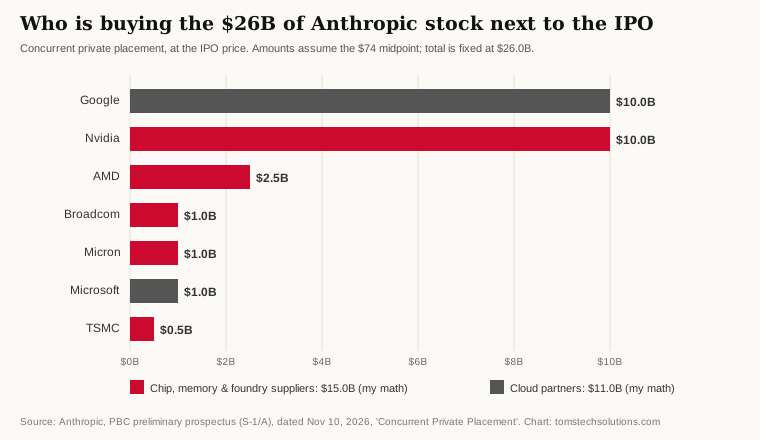
- Google ~$10.0B and Nvidia ~$10.0B
- AMD ~$2.5B
- Broadcom, Micron and Microsoft ~$1.0B each
- TSMC Partners ~$0.5B
By my math, $15.0B of that comes from companies that make the chips, memory or wafers Anthropic runs on (Nvidia, AMD, Broadcom, Micron, TSMC), and $11.0B from its cloud partners (Google, Microsoft). The placement is about 31% of the estimated net proceeds (my math: 26.0 ÷ 84.6). Two details from the filing matter. Google's purchase uses up its existing option under an earlier note agreement. AMD's purchase satisfies part of an equity commitment that's tied to its hardware supply agreement with Anthropic. And these shares aren't subject to the usual IPO lock-up, though they're unregistered "restricted securities" that can only be resold under a registration or an exemption.
Now follow the money the other way. Anthropic says it has about $900.9B of commitments for compute, data centers and leases, with $70.7B due in the 12 months after Sep 30 (prospectus). Two weeks ago, in my $895B compute bill post, those numbers were $895.4B and $69.8B. Both went up in two weeks. Per the filing, Anthropic gets its Nvidia GPUs through a strategic partnership with Nvidia plus arrangements with Microsoft, SpaceXAI, Nscale, Lambda and other cloud providers.
The everyday analogy: imagine a landlord, the hardware store, and the electric company all chipping in for the down payment on a house, because the buyer has already signed contracts to pay all three of them for the next decade. It's not a scam. Everyone has a real reason to want the deal to close. But if the buyer's income stumbles, everyone at the table loses at the same time.
For scale (my math): Nvidia's ~$10B check is about 47% of the $21.3B of free cash flow it generated last quarter (Nvidia Q2 release). Real money, but easily affordable.
What is Anthropic worth? The valuation math
The bull number, straight from the prospectus: run-rate revenue was about $81B as of Oct 31, up $10B from Sep 30. The filing itself warns run-rate isn't a forecast and its recent growth "may not be sustainable."
What the banks are modeling, per Reuters' sources:
| Year | Sell-side revenue estimate |
|---|---|
| 2026 | ~$52B to $53B |
| 2027 | ~$135B to $137B |
| 2028 | ~$270B to $280B (the year banks anchor valuation on) |
Some buy-side forecasts run 10% to 15% higher for 2026 and 2027. One investor who passed is about 30% below the sell-side for 2028.
My rough math, using the top-of-range $1.405T (and treating it like a price-to-sales multiple, which is a simplification):
- About 17x the $81B run-rate (1,405 ÷ 81).
- About 5x the midpoint of the 2028 estimate (1,405 ÷ 275).
So the price is basically a bet that 2028 shows up roughly on schedule. And here's the infrastructure catch: the $70.7B due in the next 12 months is about 87% of today's run-rate (my math: 70.7 ÷ 81). The company has the cash for it, roughly $132B in cash and short-term investments per CNBC, before IPO money. It's not a solvency question this year. It's a question of whether revenue keeps compounding fast enough to grow into contracts that run to 2045.
Anthropic's own line in the filing explains why it keeps signing: "In the past, we have significantly underestimated our compute requirements." That's a company more afraid of running out of GPUs than of owing too much for them.
Why the order matters
Nvidia goes first, and that's not trivial.
- If Nvidia beats and guides Q4 above consensus (about $124.6B per Benzinga's consensus table), it says demand for compute is still running hot. That's the best possible backdrop for a company whose whole pitch is "we need more compute."
- If Nvidia disappoints, or Kress's commentary sounds shaky, Anthropic prices the next night into a nervous tape. Bankers can still get the deal done on a 6x book. But "price at the top of the range" becomes "price in the middle."
- If Anthropic prices above the range and trades up, that matters for everyone who rents it compute. As CNBC points out, Google is backstopping $19B of Anthropic lease commitments to TeraWulf (my breakdown of that deal), and neocloud deals like Nscale's and Lambda's are built on Anthropic contracts (see my compute bill post). A strong public stock makes those contracts look safer to every bank in the chain.
The backdrop isn't friendly. CNBC notes the Nasdaq fell 5.3% in October, rising rates pushed investors out of debt-heavy neoclouds, and Nvidia shares fell 13% last week.
What I think
- This week is a referendum on the demand side, not the chip side. Nobody doubts Nvidia can ship. The question is whether the AI labs that buy the compute can raise money fast enough to pay for it. Anthropic's IPO is that question with a price tag on it.
- The circularity is real, and also rational. Nvidia's own CFO commentary said AI clouds and model makers are "growing faster than their balance sheets and long-term credit profiles can support." The supplier stake is Nvidia, AMD and friends putting their money where their order books are. I'm fine with that as long as everyone reports it clearly, and this prospectus does.
- The number I care about most on Tuesday isn't revenue. It's the supply commitments line and the receivables. If Nvidia is still locking up memory for years and customers are still paying on time, the buildout is intact no matter what the stock does.
- The number I care about most on Wednesday is the price versus the range. At the top of the range, the market accepts the 2028 story. Above it, the market is paying ahead of it. Below it, the AI trade has a problem bigger than one CEO.
- I could be wrong about how much these two events feed off each other. My instinct is that a deal with a 6x book gets done regardless of one day's market. But I wouldn't bet on the tape not mattering this week.
What I'm watching next
- Tuesday, Nov 17, ~1:20 p.m. PT: Nvidia Q3 FY27. Revenue vs. $108.0B guide and ~$109.3B consensus, Rubin revenue, the Q4 guide, supply commitments, receivables days, and any update on China. I'll break down the print here Wednesday morning.
- Wednesday, Nov 18 (evening): Anthropic pricing. Inside, above, or below $70 to $78, and whether the deal is upsized.
- Thursday, Nov 19: ANT's first trade, and how Nvidia, AMD, Broadcom and the neoclouds move on the day. I'll cover how the debut went once there's real trading data.
- Still pending: Nvidia's CEO search, and Huang's expected testimony in Congress, both from my Nov 14 post.
Not investment advice. I don't know how either event will go, and nobody else does yet either.